Merchant GuidesLatest
Card Surcharge Ban: What Businesses Can Still Do
Card surcharges are ending, but businesses still have options.
card surcharge ban Australiapayment method discountszero transaction fees
6 min · 1 October 2026Read Article
Guides, explainers, and industry news to help Australian merchants and consumers navigate the changing payments landscape, including guidance on the October 2026 card-surcharge changes.
Card surcharges are ending, but businesses still have options.
The RBA is not banning surcharges directly. Instead, it's enabling Visa, Mastercard, eftpos and American Express to impose no-surcharge rules from 1 October 2026. Understand the distinction and what it means for your business.
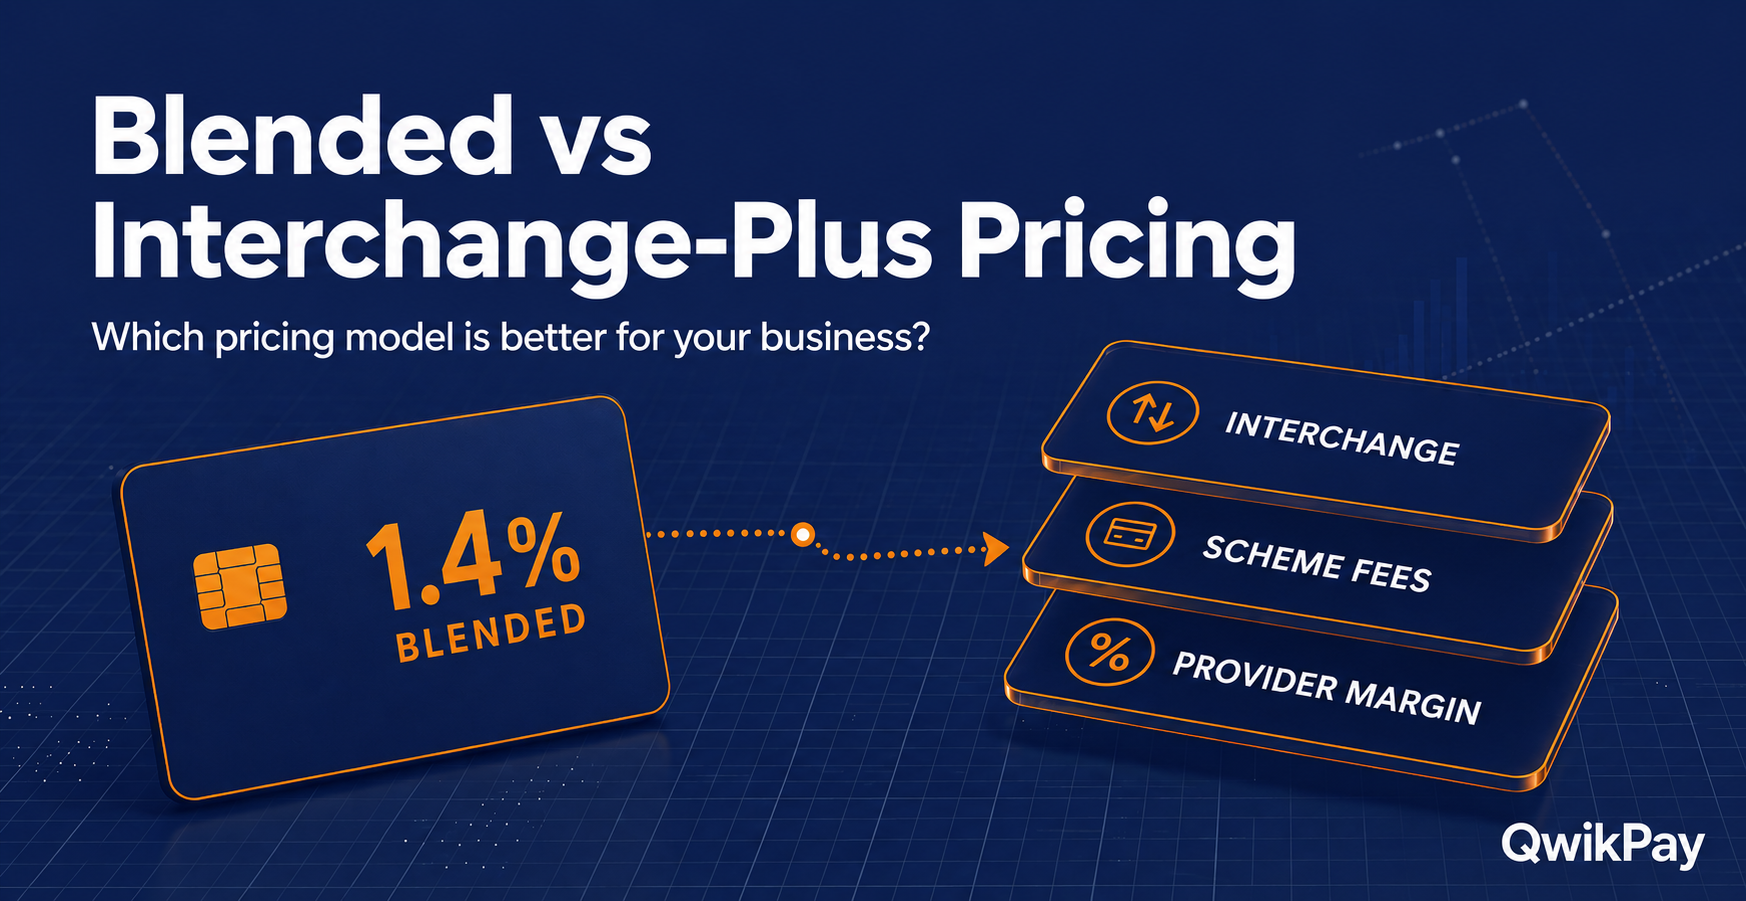
Compare blended and interchange-plus pricing models. Understand how each works, why transparency matters, and what changes when the RBA cuts interchange on 1 October 2026.
PayTo is Australia's account-to-account payment system built on the New Payments Platform. Here is how PayTo works, how PayID fits in, and how QwikPay uses PayTo to enable $0 merchant transaction fees.
From 1 October 2026, Australian merchants generally cannot add surcharges to eftpos, Mastercard, Visa or American Express payments. Learn which payments are covered, who is introducing the rules and how merchants can prepare.
If you want to accept card payments as a business in Australia, you need a merchant account. But merchant accounts come with fees. Here's how they work, what they cost, and why more small businesses are looking for alternatives.
Card networks charge 0.85–2% on every transaction. From October 2026, merchants cannot apply card surcharges to Visa, Mastercard and eftpos. Here is how QR code payments via QwikPay remove the fee entirely - not just reduce it.
Add QwikPay alongside your existing payment setup. Join before 1 October 2026 and receive 12 months of merchant access free.
No lock-in contract. Eligibility, onboarding requirements and QwikPay terms apply.